Table of Contents
Highlights
- Great banks for small business should match a company’s cash-handling needs, branch preferences, lending goals, software integrations, and international payment requirements.
- Founders comparing great banks for small business should review monthly fees, waiver rules, transaction limits, cash deposit allowances, wire costs, and APY before opening an account.
- Traditional institutions may be among the great banks for small business for cash-heavy companies that need branches, teller support, merchant services, and lending products.
- Online banking platforms can rank among the great banks for small business for digital-first companies seeking lower fees, automation, accounting integrations, and yield-bearing balances.
- Companies evaluating great banks for small business should verify FDIC insurance, sponsor-bank details, pass-through coverage, and the mechanics of any sweep program.
- A practical approach to finding great banks for small business is to compare three to five providers and consider combining an online account for automation with a traditional account for branch access and credit relationships.
For U.S. founders, discovering great banks for small business operations depends on how an enterprise collects revenue and manages disbursements. Chase, Bank of America, and Wells Fargo suit enterprises needing physical branches and regular currency deposits. Meanwhile, digital financial platforms like Bluevine, Grasshopper, Novo, Mercury, and Airwallex deliver lower monthly service expenses, sophisticated automation tools, and streamlined interfaces for domestic and cross-border commercial transactions.
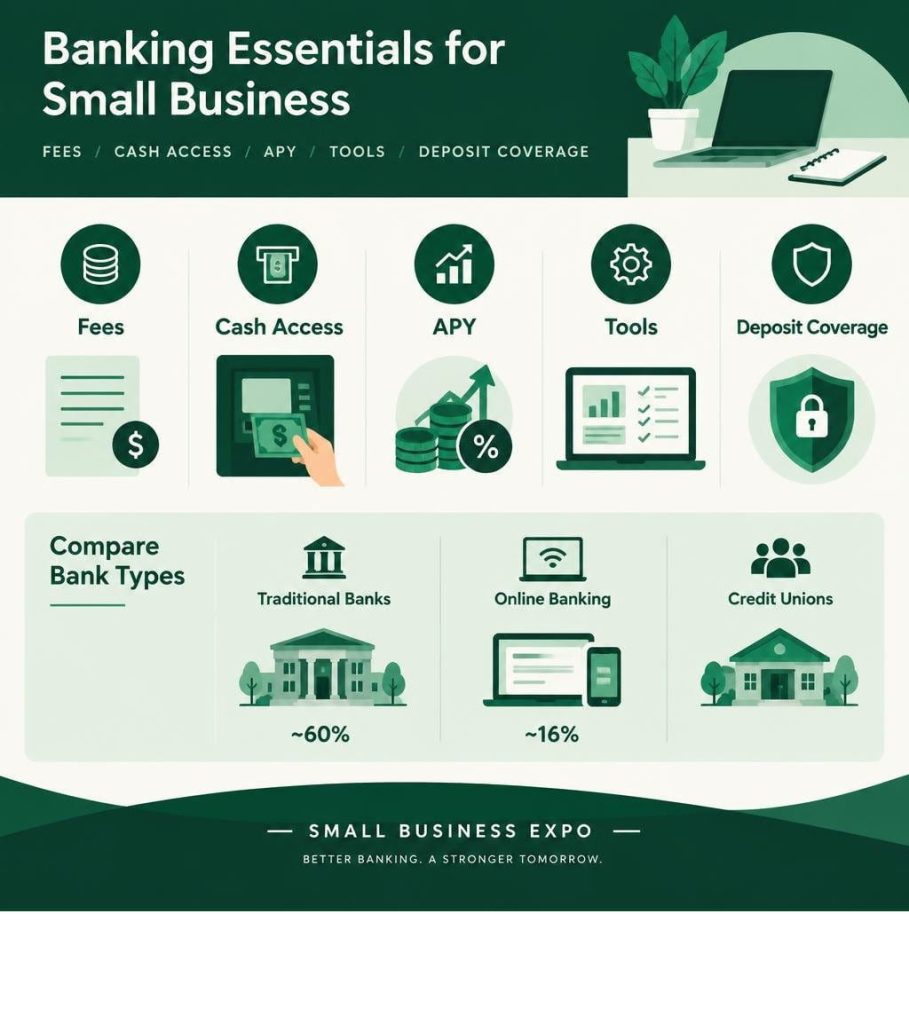
Selecting great banks for small business checking and treasury management requires evaluating core functional categories:
- Cash-heavy retail storefronts: Physical branch locations, direct teller deposits, and expansive commercial ATM access
- Freelance operators and emerging startups: Zero monthly maintenance fees, integrated digital invoicing, and accounting platform sync
- Expanding commercial firms: Merchant processing, multi-user corporate debit cards, granular expense permissions, and credit line access
- Enterprises holding operating capital: Yield-bearing commercial checking, high-yield business savings, or money market accounts
- International e-commerce sellers: Multi-currency balance management and transparent foreign exchange rates
Monthly service charges impact operational profitability. Chase Business Complete Banking charges a $15 monthly service fee, waivable through qualifying account activities or maintaining a $2,000 minimum daily balance. Bank of America Business Advantage Fundamentals carries a $16 monthly charge following initial promotional periods, with fee waivers accessible through qualifying balance thresholds or designated monthly commercial debit card transactions.
Digital-first depository solutions diminish overhead, but cash-reliant companies must assess physical deposit workflows, partner retail deposit networks, and transaction caps. Deposit safety remains critical: traditional commercial bank balances carry direct FDIC insurance coverage up to statutory limits, whereas fintech platforms employ program bank sweep networks to extend protection across multiple institutions.
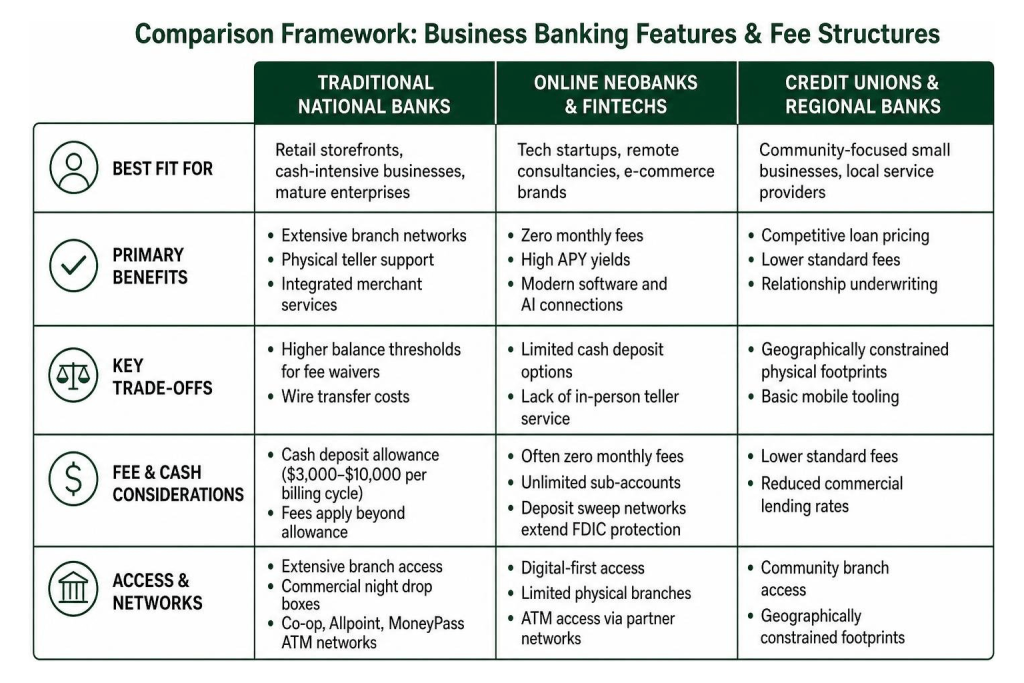
The detailed comparative analysis below outlines baseline account fees, cash handling rules, annual yields, treasury software utilities, branch footprints, and new account incentives for commercial operators evaluating great banks for small business expansion.
This content is for general informational purposes only and is not legal, tax, or financial advice. Small Business Expo is not a law firm and does not provide legal services or act in any legal capacity. Consult your lawyer, tax professional, or financial advisor before acting on these steps.
Traditional Banks vs. Online Banking vs. Credit Unions
Selecting an appropriate commercial depository requires understanding structural differences across banking models in the United States. In the domestic commercial landscape, small business owners choose between established brick-and-mortar commercial banks, online banking platforms, and local credit unions to minimize transaction fees and streamline daily workflows. Discovering great banks for small business sustainability begins with evaluating these institutional formats as of September 2026.
Managing overhead demands structured financial planning, particularly when managing business cost pressures in 2026. Commercial account selection directly influences fee structures, team expense tracking, and operational cash liquidity across all growth cycles.
|
Institution Type |
Best Fit For |
Primary Benefits |
Key Trade-Offs |
|---|---|---|---|
|
Traditional National Banks |
Retail storefronts, cash-intensive companies, mature operations |
Extensive branch footprints, dedicated teller support, integrated merchant services |
Higher balance thresholds for fee waivers, higher domestic wire fees |
|
Online Neobanks & Fintechs |
Tech startups, remote service firms, domestic digital brands |
Zero monthly fees, competitive variable APY yields, modern software connections |
Limited cash deposit options, lack of in-person teller service |
|
Credit Unions & Regional Banks |
Community-focused small businesses, local service providers |
Competitive loan pricing, lower standard fees, relationship underwriting |
Geographically constrained physical footprints, basic mobile tooling |
Comparing Physical Branches vs Online Great Banks for Small Business
Brick-and-mortar institutions provide physical operational infrastructure across U.S. communities. Retail storefronts, dining establishments, and trade contractors routinely handle physical currency. For these enterprises, direct teller access and night deposit drop boxes remain indispensable. Products such as Chase Business Complete Banking combine branch deposits with digital card processing tools like Chase QuickAccept to streamline daily reconciliations for leaders seeking great banks for small business efficiency.
Conversely, online platforms provide automated financial administration. Digital providers bypass physical real estate overhead to deliver fee-free checking, automated tax allocation sub-accounts, and real-time ledger synchronization. Digital platforms also partner with chartered institutions to deploy deposit sweep networks that provide expanded pass-through FDIC protection, provided customer funds are properly transferred and maintained in accordance with federal custodial requirements.
Credit Unions and Regional Institutions for Growth
Credit unions and community banks operate under member-owned or localized models, channeling earnings back to depositors through reduced commercial loan rates and reduced maintenance charges.
Entrepreneurs seeking equipment financing or commercial real estate backing benefit from understanding how small business loans typically work. Regional partners often deliver personalized underwriting flexibility that automated algorithms cannot replicate, bridging national banking capabilities with localized portfolio management.
Key Features and the OPERATE Framework for Great Banks for Small Business
Selecting great banks for small business growth requires evaluating fee schedules, cash limits, and integration capabilities against broader operational priorities in September 2026. Securing dependable commercial accounts provides the groundwork for building strong business credit and accessing working capital.
The OPERATE Framework: Aligning Banking with Small Business Challenges
Managing a U.S. enterprise involves multifaceted operational demands, including lead generation, SEO, social media marketing, hiring, health insurance administration, website optimization, and AI integration. Great banks for small business management provide the financial backbone to solve these challenges through the OPERATE framework:
- O – Operational Spend Categorization: Allocating dedicated sub-accounts for digital marketing, social media campaigns, and lead generation ad spend to track customer acquisition costs accurately.
- P – Payroll and Benefits Infrastructure: Linking primary commercial checking accounts with automated payroll systems to administer employee wages, health insurance stipends, and worker benefits seamlessly during hiring expansions.
- E – E-Commerce and Digital Optimization: Connecting commercial bank accounts to payment gateways, website optimization tools, and conversion tracking suites to maintain steady domestic cash inflow.
- R – Resource Scaling via AI Integration: Pairing specialized AI financial forecasting tools with expert human marketing agencies and certified accounting professionals, ensuring data-driven scaling without sacrificing human strategic oversight.
- A – Automated Tax and Reserve Buckets: Setting up automated rules to route a percentage of gross revenues into separate tax and emergency savings reserves.
- T – Treasury and High-Yield Growth: Holding operating reserves in high-yield commercial vehicles with competitive variable yields to offset inflation on working capital.
- E – Expense Controls and SEO Investment: Issuing customizable corporate debit cards to track recurring software investments for SEO, content creation, and analytics tools.
Cash Handling, Branch Access, and ATM Networks
Cash handling requires transparent policies. Traditional institutions generally provide a monthly cash deposit allowance—often ranging from $3,000 to $5,000 per billing cycle—without surcharges. Once an entity exceeds these thresholds, cash handling fees typically apply per $100 deposited.
Businesses operating across major metropolitan markets like Chicago, Boston, Atlanta, or Dallas require dependable ATM networks. Co-op, Allpoint, and MoneyPass networks enable fee-free cash withdrawals nationwide across the United States. Institutions providing specialized Small Business Banking Solutions deliver structured cash allowances alongside extensive branch accessibility, a hallmark of great banks for small business retail operations.
Bookkeeping, Invoicing, and Expense Management
Modern commercial accounts serve as primary operational hubs. Leading checking accounts provide direct synchronization with enterprise platforms such as QuickBooks, Xero, and Gusto. Built-in digital invoicing systems allow business owners to bill clients directly and accept ACH transfers without third-party gateways.
Adhering to essential bookkeeping best practices prevents compliance issues and tax-season discrepancies. Implementing software automation alongside professional accounting oversight supports streamlined small business accounting across all growth phases, demonstrating why these features distinguish great banks for small business operations from generic deposit accounts.
Comparative Review of Business Checking and Savings Accounts for Founders
Founders should evaluate financial institutions based on overall operational value, fee mitigation, and working capital access in September 2026. An effective strategy involves evaluating the best banks for small business against current revenue models and cash flow patterns. This evaluation of great banks for small business enterprises highlights the account tiers, fees, and variable yields substantiated as of September 2026.
Traditional National Institutions: Chase, Bank of America, and Wells Fargo
National commercial banks maintain extensive branch footprints, comprehensive treasury tools, and dedicated merchant systems, serving as traditional great banks for small business operations requiring physical branch support:
- Chase Business Complete Banking: Features a $15 monthly service fee, waivable with a $2,000 minimum daily balance, qualifying Chase Ink business card purchases, or eligible deposits through Chase QuickAccept. Includes unlimited electronic deposits and $5,000 in monthly fee-free cash deposits.
- Bank of America Business Advantage: The Fundamentals tier costs $16 per month, waived with a $5,000 combined average monthly balance or $500 in monthly debit card spending. The Relationship tier offers expanded transaction allowances for companies holding at least $15,000 in combined balances.
- Wells Fargo Initiate Business Checking: Requires a $15 monthly maintenance fee, waivable via a $2,000 daily minimum balance or a $5,000 average combined deposit balance. It accommodates up to 100 fee-free posted transactions and $3,000 in monthly cash deposits.
Online and Fintech Great Banks for Small Business
Digital banking platforms deliver streamlined account creation, modern software integrations, and reduced maintenance charges, establishing them as strong candidates among great banks for small business founders seeking minimal overhead in September 2026:
- Grasshopper Bank: The Grasshopper Innovator Checking product provides competitive variable annual percentage yields on checking balances alongside 1% cash back on qualifying debit transactions and fee-free ACH transfers.
- Novo: Novo Free Business Checking provides a no-fee checking structure tailored for freelancers and digital enterprises, integrating seamlessly with Stripe, Shopify, and major accounting suites.
- Mercury: Built specifically for venture-backed and bootstrapped tech startups in the United States, Mercury Online Business Banking offers no-fee domestic wire transfers, advanced multi-user permissioning, and competitive treasury management tools for surplus operating cash.
High-Yield Business Savings and Reserve Accounts
Maintaining liquid reserves allows companies to earn interest on idle operational capital while preserving cash flow flexibility. Competitive business savings and money market options among great banks for small business management as of September 2026 include:
- Live Oak Bank: Delivers a 2.75% variable APY as of September 2026 on business savings balances with no monthly maintenance fees or minimum balance constraints.
- American Express Business Checking: Provides a 1.00% variable APY as of September 2026 on eligible balances up to $500,000 without monthly maintenance charges.
- Bluevine Business Checking: Offers a 1.30% variable APY as of September 2026 on balances up to $250,000 for accounts meeting baseline monthly debit card activity criteria, solidifying its place among great banks for small business reserve allocation.
How to Open a Business Bank Account Online or In-Person
Opening a commercial account requires comprehensive organizational documentation to satisfy federal Know Your Customer (KYC) and Anti-Money Laundering (AML) mandates. Many digital institutions allow complete online setup, whereas certain traditional institutions may require physical branch visits for multi-member corporate structures. Finding great banks for small business onboarding simplifies this administrative process significantly.
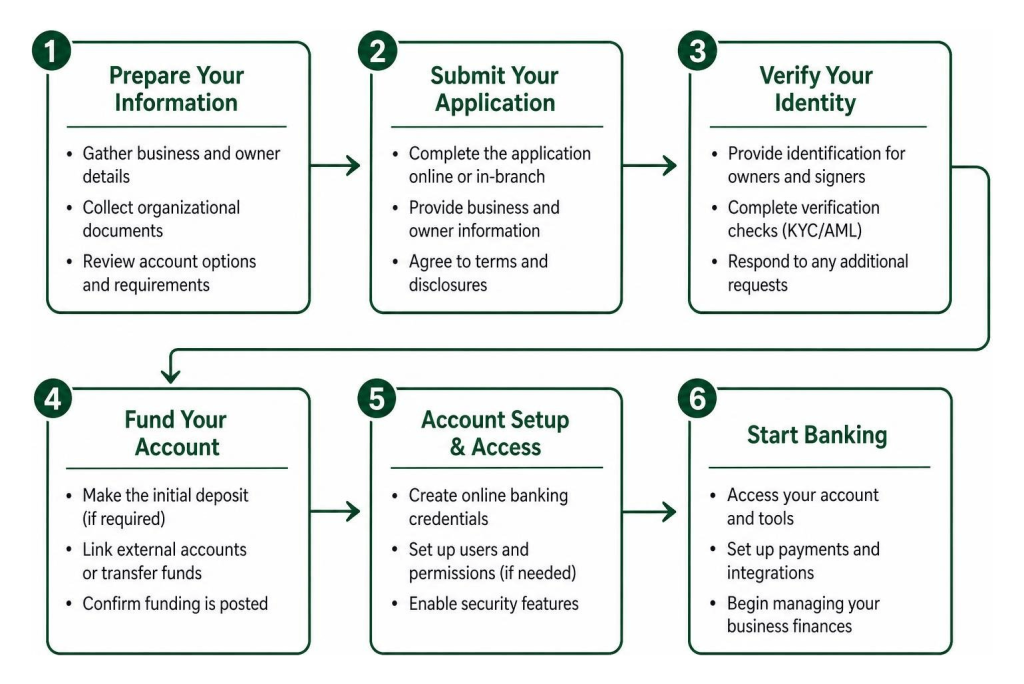
When establishing commercial relationships with great banks for small business expansion, founders can leverage federal resources and pair deposit accounts with government-backed credit lines, modern digital accounting tools, and flexible merchant solutions.
Final Thoughts
Selecting an optimal depository structure establishes the financial foundation necessary for sustainable enterprise scaling. By aligning deposit models, transaction frequencies, and treasury tools with organizational workflows, founders partnering with great banks for small business success can minimize recurring fees, manage operating overhead, and optimize cash liquidity.
Small business leaders looking to connect with commercial banking specialists, treasury managers, and B2B growth experts are encouraged to attend upcoming national industry conferences. Participating in collaborative business events enables entrepreneurs to gain actionable insights, refine operational strategies, and accelerate long-term profitability.
Frequently Asked Questions About Small Business Banking
Can a business bank account be opened entirely online?
Yes. Most digital banks, fintech platforms, and large national institutions permit single-member LLCs and sole proprietorships to complete digital onboarding. Great banks for small business founders allow applicants to upload government identification, business registration certificates, and Employer Identification Numbers (EINs) through secure verification portals.
What documentation is required to open a business account?
Financial institutions typically require:
- Federal Employer Identification Number (EIN) confirmation letter from the IRS.
- State-filed formation documents (Articles of Organization or Articles of Incorporation).
- Corporate Operating Agreement or Corporate Bylaws.
- Active commercial business licenses or DBA (Doing Business As) filings.
- Unexpired, government-issued photo identification for all beneficial owners holding 25% or greater equity.
Which business checking accounts have no monthly maintenance fees?
Institutions such as Novo, Mercury, and Grasshopper provide checking accounts without monthly maintenance charges. Additionally, traditional great banks for small business operations like Chase, Bank of America, and Wells Fargo waive monthly fees when businesses maintain minimum balances or meet monthly spending criteria.
What is the difference between Bank of America Business Advantage Fundamentals and Relationship Banking?
As of September 2026, Business Advantage Fundamentals carries a $16 monthly fee (waivable with a $5,000 balance or $500 monthly debit spend) and is tailored for early-stage operations. The Relationship Banking tier requires a $15,000 balance to waive its monthly fee and provides higher cash deposit thresholds, multiple linked checking accounts, and zero-fee incoming domestic wire transfers.
How do cash deposit limits work for retail businesses?
Institutions establish standard monthly thresholds for cash handling, generally between $3,000 and $5,000 per statement cycle. Deposits exceeding the allotted threshold incur cash handling surcharges, typically calculated as a percentage or a flat fee per $100 processed.
Which banks offer competitive variable APYs on business checking and savings?
As of September 2026, Live Oak Bank provides a 2.75% variable APY on liquid business savings, while Grasshopper Bank offers yield-bearing checking balances alongside specialized money market accounts. Bluevine offers a 1.30% variable APY on qualifying checking balances up to $250,000 for accounts meeting monthly transaction thresholds.
How does FDIC insurance coverage apply to fintech accounts and sweep programs?
Standard FDIC insurance covers up to $250,000 per depositor, per insured bank, for each account ownership category. Fintech platforms are technology companies rather than chartered banks; they hold customer funds in custodial accounts at partner banks or distribute them across multiple institutions using sweep networks. Pass-through coverage applies only if funds are successfully swept to insured institutions, appropriate individual ownership records are maintained, and the partner bank remains solvent.