Table of Contents
Highlights
- Employers can choose among fully insured, level-funded, ICHRA, QSEHRA, and self-funded small business health plans based on risk tolerance, budget predictability, workforce needs, and administrative capacity.
- Fully insured small business health plans provide fixed monthly premiums and transfer employee-claim risk to the insurance carrier, making them suitable for employers prioritizing simplicity.
- Level-funded small business health plans combine fixed monthly payments with claims funding and stop-loss coverage, potentially returning a year-end surplus when claims remain below projections.
- ICHRA programs suit employers seeking flexible, defined contributions, while QSEHRA programs serve employers with fewer than 50 FTEs and 2026 reimbursement limits of $6,450 for individual coverage and $13,100 for family coverage.
- Eligible employers can receive a federal tax credit covering up to 50% of premiums for qualifying small business health plans when they meet employee-count, wage, contribution, and SHOP purchasing requirements.
- Businesses with fewer than 50 FTEs generally are not required to offer small business health plans, while Applicable Large Employers with at least 50 FTEs must offer affordable minimum-value coverage to at least 95% of full-time employees.
Selecting the most suitable coverage structure requires evaluating how financial risk is distributed between the enterprise and the insurance carrier. In the United States commercial market, employers evaluate diverse small business health plans. Organizations generally select from five core models: traditional fully insured plans, level-funded arrangements, Individual Coverage Health Reimbursement Arrangements (ICHRAs), Qualified Small Employer Health Reimbursement Arrangements (QSEHRAs), and traditional self-funded plans. Exploring options for small business health coverage allows leadership teams to align company budgets with workforce wellness goals when comparing commercial healthcare options.
Disclaimer: This content is for general informational purposes only and is not legal, tax, or financial advice. Small Business Expo is not a law firm and does not provide legal services or act in any legal capacity. Consult your lawyer, tax professional, or financial advisor before acting on these steps.
|
Plan Model |
Primary Risk Bearer |
Monthly Cost Predictability |
Regulatory Framework |
Best Suited For |
|---|---|---|---|---|
|
Fully Insured Group |
Insurance Carrier |
High (Fixed premiums) |
State Insurance Law & ACA |
Teams seeking minimal administrative complexity and zero claims liability. |
|
Level-Funded Hybrid |
Employer (Capped via Stop-Loss) |
High (Predictable monthly payments) |
ERISA (Exempt from state premium taxes) |
Healthy workforces wanting potential year-end surplus refunds. |
|
ICHRA |
Individual Employee |
Maximum (Defined employer allowance) |
ACA / Federal IRS Regulations |
Multistate remote teams and companies wanting customized contribution classes. |
|
QSEHRA |
Individual Employee |
Maximum (Strict statutory caps) |
IRS Section 9831(d) |
Businesses with under 50 FTEs seeking simple, tax-free medical reimbursements. |
|
Self-Funded Group |
Employer |
Variable (Requires cash reserves) |
ERISA |
Larger small businesses (25–50+ FTEs) with stable cash flow and claims data. |
Traditional Fully Insured Group Policies
Traditional fully insured small business health plans represent the classic approach to commercial coverage. Under this structure, the company pays a fixed monthly premium directly to a commercial insurance carrier, such as an established regional or national insurer offering dedicated small business group plans. In exchange, the insurance carrier assumes all underlying medical and financial risk associated with employee claims.
These policies are regulated by state insurance departments and must incorporate all ACA Essential Health Benefits. Premiums for fully insured small group policies are generally determined through community rating standards based on geographic territory, family status, and the ages of enrolled staff members. While fully insured group plans protect companies from unexpected medical catastrophes, they offer zero financial return if employee healthcare utilization remains low throughout the policy year.
Fully Insured vs Level-Funded Health Plans
Level-funded small business health plans operate as a hybrid mechanism between fully insured models and self-insured plans. Under a level-funded arrangement, the enterprise pays a fixed, level monthly payment to a third-party administrator (TPA). This payment is split into three specific components:
- An administrative fee covering operational management and customer support.
- An individual and aggregate stop-loss insurance premium protecting the firm against high-cost claims.
- A dedicated claims funding account allocated toward everyday medical expenses.
Because level-funded structures are governed under the federal Employee Retirement Income Security Act (ERISA), they are typically exempt from state premium taxes, which normally add 2% to 3% to traditional group rates. If actual claims remain below the funded amount at the close of the policy year, the business receives a surplus refund or a premium credit upon renewal. If claims exceed the budgeted pool, the stop-loss insurance policy absorbs the excess costs without altering the agreed-upon monthly payment for these hybrid arrangements.
Health Reimbursement Arrangements: ICHRA and QSEHRA Models
Health Reimbursement Arrangements (HRAs) represent a defined-contribution approach to modern small business health plans. Rather than purchasing a collective master policy, the enterprise provides tax-free reimbursements to employees who select their own individual healthcare coverage on the open market.
For enterprises exploring how an ICHRA framework operates for small businesses, this structure provides high flexibility compared to conventional group insurance. ICHRAs have no company size restrictions and permit employers to designate distinct monthly allowance tiers across eleven legally recognized employee classes, such as salaried versus hourly, full-time versus part-time, or geographic work locations.
In contrast, a QSEHRA is restricted exclusively to employers with fewer than 50 full-time equivalent (FTE) employees who do not offer traditional group coverage. For the 2026 tax year, the IRS statutory contribution limits permit a maximum annual reimbursement of $6,450 for individual coverage and $13,100 for family coverage. Employers looking to establish these reimbursement programs can utilize specialized QSEHRA document packages to meet federal compliance guidelines. Under both models, company reimbursements are 100% tax-deductible as business expenses and arrive entirely tax-free to workers.
Association Health Plans and Self-Funded Structures
Association Health Plans (AHPs) allow multiple independent small business owners to pool their workforce numbers through a shared industry association or local chamber of commerce. By banding together across metropolitan markets like Dallas, Houston, Chicago, or Boston, small enterprises gain access to cost-effective small business health plans with negotiating leverage, administrative efficiencies, and pricing structures typically reserved for large corporate organizations.
Pure self-funded benefit designs involve the employer paying all employee healthcare claims directly out of corporate operational accounts. According to the Kaiser Family Foundation, approximately 65% of covered American workers were enrolled in self-funded plans. While self-funded arrangements deliver operational control, data transparency, and customized plan design, small firms must secure specific stop-loss coverage—often starting at a $10,000 to $25,000 attachment point per individual—to safeguard operational capital from catastrophic medical events.
Costs, Benchmarks, and Tax Incentives for Employer Coverage
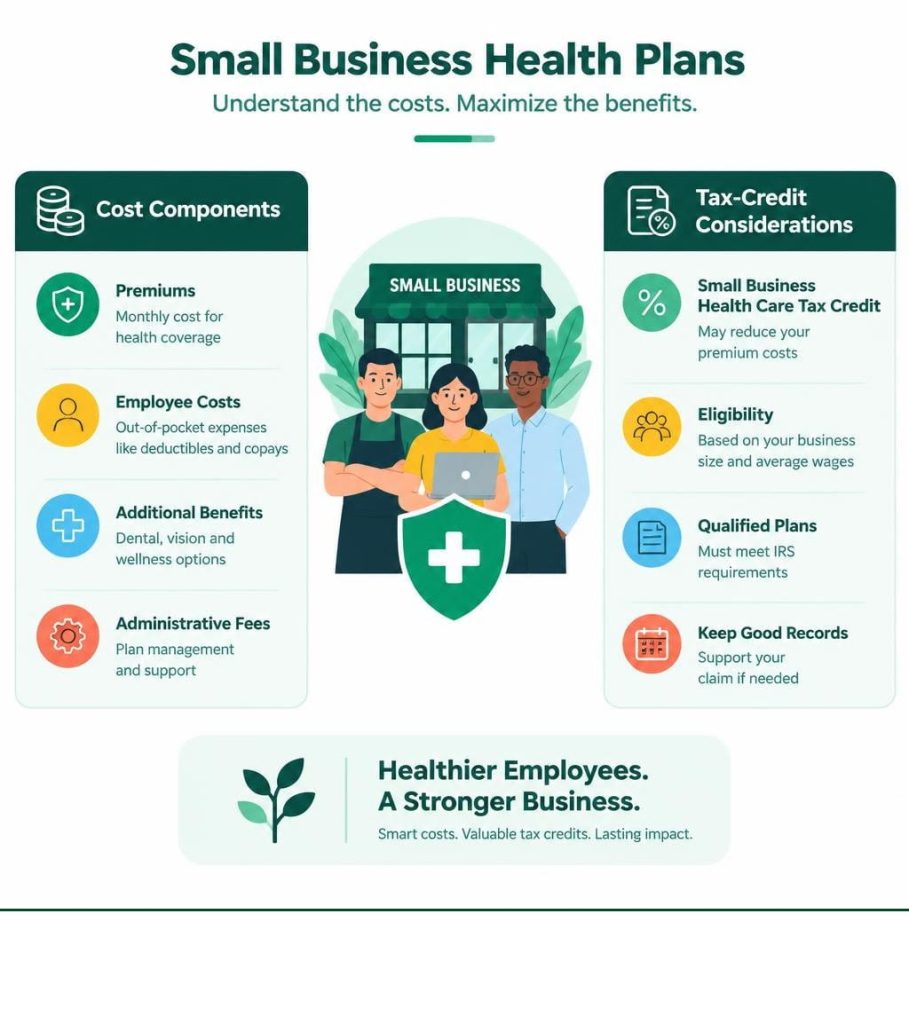
Budgeting for small business health plans requires balancing total employee compensation against operational cash flow. Detailed small business health insurance cost analyses show that group health insurance generally ranges between $8,000 and $25,000 per employee annually, depending on coverage tiers, geographic market ratings, and workforce age demographics.
Average Premium Costs and Contribution Split Requirements
When funding small business health plans on a national level, employers pay an average of $6,485 annually for each covered individual and $13,737 for each covered family tier. The 2026 national average Silver plan premium runs approximately $703 per month for single coverage under standard group policies. Most small business owners cover 70% to 83% of the employee-only premium cost, leaving the employee to cover the remainder via pre-tax payroll deductions.
To maintain active commercial small business health plans, insurance carriers typically establish two contractual baseline rules:
- Minimum Contribution Rule: The employer must contribute at least 50% of the employee-only premium for the lowest-cost baseline plan offered.
- Minimum Participation Rule: Between 50% and 75% of eligible, non-waiving staff members must enroll in the policy. Employees who waive coverage due to enrollment in a spouse’s group plan, Medicare, or military benefits are excluded from the participation denominator calculation.
Qualifying for the Small Business Health Care Tax Credit
The federal government provides a targeted incentive known as the Small Business Health Care Tax Credit under Internal Revenue Code Section 45R to lower the cost of qualifying employee coverage. Qualifying employers can access these savings by purchasing qualified coverage through the official SHOP portal for small employers.
To qualify for the Form 8941 tax credit in 2026 for small business health plans, an enterprise must fulfill four criteria:
- Workforce Size: Employ fewer than 25 full-time equivalent (FTE) employees during the tax year.
- Wage Limits: Maintain average annual non-owner employee wages of $62,000 or less.
- Employer Contribution: Fund at least 50% of the single-coverage premium cost for small group coverage.
- Certified Marketplace Purchasing: Purchase the group policy via the federal Small Business Health Options Program (SHOP) or a state-based exchange.
The maximum credit covers up to 50% of employer-paid premiums for qualified small business health plans for for-profit enterprises (35% for registered tax-exempt 501(c) nonprofits). The full 50% credit applies when average employee wages remain at or below $34,100 with 10 or fewer FTEs, phasing out as staff counts approach 25 FTEs and average wages near $62,000. This federal credit is available for two consecutive tax years when sponsoring qualifying small business health plans.
Provider Network Frameworks: HMO, PPO, EPO, and HDHP Options
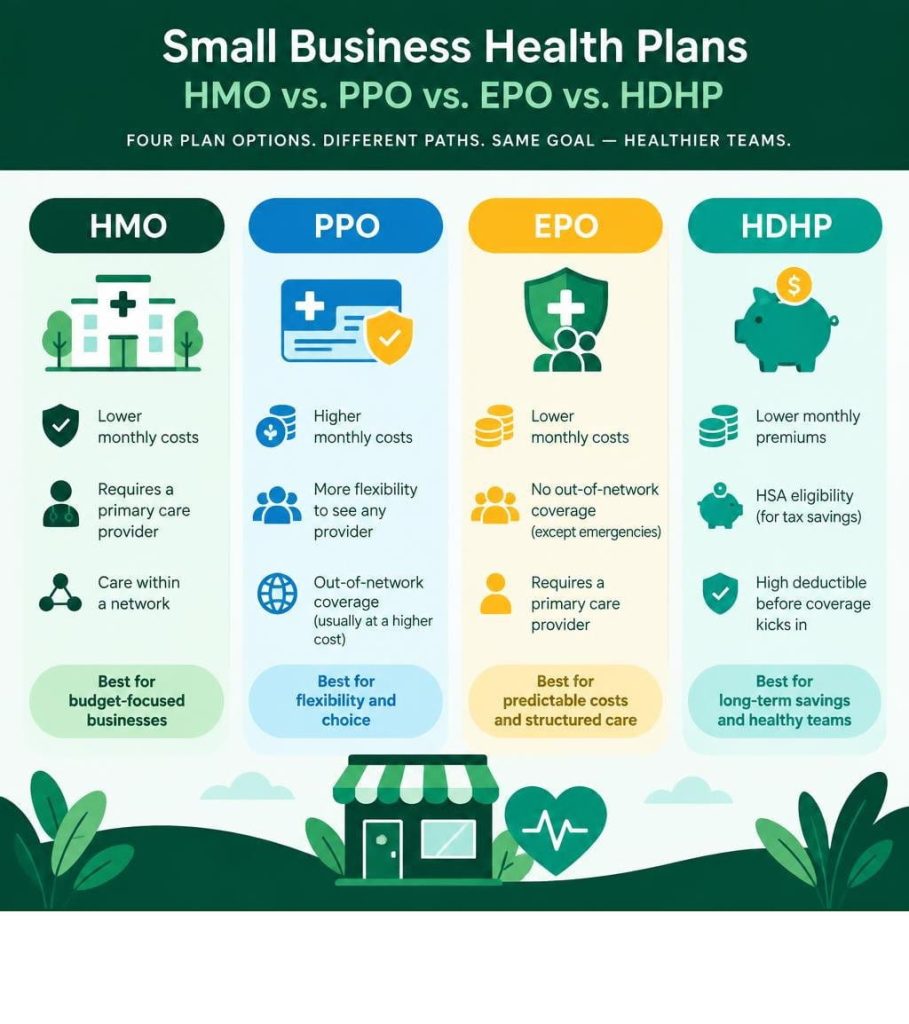
When setting up small business health plans, owners must choose a managed care framework. This choice dictates which physicians, hospitals, and medical networks employees can access, while setting out-of-pocket deductibles and monthly costs across different plan designs.
Network Flexibility vs Cost Controls
When structuring small business health plans, network options balance provider choice against premium expenses:
- Health Maintenance Organization (HMO): Requires members to choose an in-network Primary Care Physician (PCP) who coordinates all care and provides referrals for specialist visits. Out-of-network care is excluded from coverage except in emergency situations. HMO structures provide the lowest premium rates.
- Preferred Provider Organization (PPO): Delivers the highest flexibility, allowing employees to visit any specialist or hospital inside or outside the preferred network without a PCP referral. In-network visits carry lower cost-sharing, while out-of-network visits require higher member coinsurance.
- Exclusive Provider Organization (EPO): Functions as a hybrid structure for employer healthcare strategies. Employees do not need specialist referrals, but services are covered only within the designated provider network. Premiums are lower than comparable PPOs.
- High-Deductible Health Plan (HDHP): Features higher upfront annual deductibles paired with lower monthly premiums across qualifying small group plans. HDHPs can be combined with tax-advantaged financial savings accounts.
Health Savings Accounts and Preventive Care Perks
An HDHP paired with a Health Savings Account (HSA) offers a triple-tax advantage within small business health plans: employer and employee contributions are pre-tax, investment balances grow tax-free, and withdrawals for qualified medical expenses remain completely exempt from income tax.
Under the ACA, all qualifying small business health plans must provide zero-dollar preventive care visits, covering routine checkups, immunizations, and annual mammograms without requiring copayments or deductible payments. Leading carriers offering commercial small business health plans also include 24/7 dedicated virtual urgent care visits and discounted prescription tiers, which can generate significant annual medication savings for staff members.
Key Steps to Implement and Manage Employee Benefits
Deploying competitive small business health plans requires balancing workforce expectations against administrative workloads. Research indicates that 45% of small enterprise founders spend at least one full business day every week managing administrative and human resource tasks. Implementing modern HR software and automated benefit administration platforms helps streamline ongoing compliance and enrollment procedures for employee benefit programs.
Assessing Workforce Needs and Setting Coverage Tiers
The selection process begins with a detailed employee census assessing demographic factors, geographic locations across regional hubs like New York City, Atlanta, Miami, or Phoenix, and baseline preferences for workforce health coverage. Conducting internal surveys helps owners determine whether employees prioritize wide provider access (PPO structures) or lower monthly payroll deductions (HMO and HDHP arrangements) when selecting small business health plans.
For teams distributed across several states, an ICHRA model prevents the operational headache of maintaining separate regional group policies across multiple jurisdictions. Business owners can evaluate customized small business health plans through small business health insurance frameworks to align coverage tiers with workforce demographics and budget forecasting models.
How to Select and Budget for Small Business Health Plans
When evaluating proposals for small business health plans, leadership teams must examine the comprehensive Summary of Benefits and Coverage (SBC) across multiple carrier quotes rather than focusing exclusively on top-line premiums. Small enterprise owners evaluating benefit options should examine maximum out-of-pocket exposure limits, prescription drug form lists, and network provider density in operational markets.
Consulting with licensed benefit advisors and holding open employee information sessions ensures staff members understand their deductible responsibilities, preventive perks, and digital telehealth tools before coverage begins. Conducting an annual market review ensures small business health plans remain financially competitive as the company expands.
Final Thoughts
Structuring competitive small business health plans through small business health insurance is a strategic operational priority for growing American enterprises. While navigating healthcare markets requires balancing budgets, compliance rules, and plan structures, offering quality small business health plans remains one of the most effective levers for hiring skilled workers and boosting workplace productivity. Research confirms that 88% of job candidates evaluate medical, dental, and vision benefits when deciding between employment offers.
By comparing traditional group policies, hybrid level-funded options, and defined-contribution ICHRA or QSEHRA models, business owners can design optimized small business health plans that protect company capital while supporting employee health. To connect with industry peers, explore modern HR management technologies, and attend expert-led educational seminars on small business scaling, join growing entrepreneurs across the nation by registering to attend upcoming Small Business Expo events. Discover practical frameworks, innovative resources, and strategic partners at America’s premier small business networking conferences.
Frequently Asked Questions About Small Business Coverage
Are small businesses legally required to offer small business health plans?
Under the ACA Employer Shared Responsibility provisions, businesses with fewer than 50 full-time equivalent (FTE) employees are not legally mandated to provide group medical benefits. Companies that employ 50 or more FTE workers are categorized as Applicable Large Employers (ALEs) and must offer affordable coverage providing minimum essential value to at least 95% of their full-time staff to avoid financial penalties.
How much do small business health plans typically cost per employee in 2026?
National baseline Silver plan premiums run approximately $703 per month for individual coverage under commercial employer policies. The average employer contributes between 70% and 83% of this premium cost—equating to roughly $490 to $580 per employee monthly before accounting for federal tax credits. Across a team of 10 employees, employer expenses for group healthcare average between $59,000 and $70,000 annually, which can be halved during eligible Form 8941 SHOP tax credit windows.
What is the Small Business Health Options Program (SHOP)?
The Small Business Health Options Program (SHOP) is a specialized marketplace established under the ACA to assist employers with 1 to 50 employees in purchasing small business health plans and dental coverage. Operated through HealthCare.gov in federally facilitated states and via state-based portals in select markets, SHOP allows year-round enrollment and serves as the single legal pathway for small employers to claim the Form 8941 Small Business Health Care Tax Credit for small group coverage.
What is the difference between an ICHRA and a QSEHRA?
A QSEHRA is restricted to enterprises with fewer than 50 FTEs that do not maintain any active group health policies, and it enforces strict annual IRS reimbursement caps ($6,450 single / $13,100 family in 2026). An ICHRA is available to businesses of any operational size, has no statutory contribution maximums, and allows the employer to establish varied monthly reimbursement amounts across distinct employee classes when establishing employer reimbursement accounts.
How does a level-funded health plan save money?
Level-funded small business health plans lower total overhead by operating under federal ERISA standards, which bypass state insurance premium taxes (saving 2% to 3% annually). Additionally, monthly payments for level-funded structures are split into administrative costs, stop-loss insurance, and an actual claims account. If the workforce files fewer claims than projected over the policy term, the enterprise receives a refund of the remaining claims surplus at the end of the year.
What minimum participation and contribution rules apply to small employers?
Most commercial insurance carriers offering small business health plans require employers to contribute at least 50% toward the employee-only premium of their baseline coverage tier. Furthermore, insurance carriers enforce a minimum employee participation rate—typically between 50% and 75% of eligible workers. Staff members who formally waive enrollment due to existing coverage under a spouse’s employer plan, Medicare, Medicaid, or military insurance are excluded from the participation calculation for employer group plans.
Can business owners participate in small business health plans?
Participation eligibility in employer health plans depends strictly on the legal entity structure of the enterprise:
- C-Corporations: Owner-employees are categorized as standard W-2 employees and can participate fully in group coverage, ICHRAs, and tax-advantaged health programs on a pre-tax basis.
- S-Corporations: More-than-2% shareholders cannot receive tax-free benefits through cafeteria plans or standard HRAs; however, their health insurance premiums paid by the business under small business health plans are reported as W-2 wages and can be deducted on individual Form 1040 tax returns.
- LLCs and Sole Proprietorships: Partners and sole owners are not W-2 employees and cannot participate tax-free in standard group HRAs, but they can deduct their personal health insurance premiums as an adjustment to income on personal returns.