Table of Contents
Small business finances can become closely intertwined with personal finances when keeping a company running requires putting personal resources into the equation. New Small Business Expo Research Team survey data shows just how common that overlap can be.
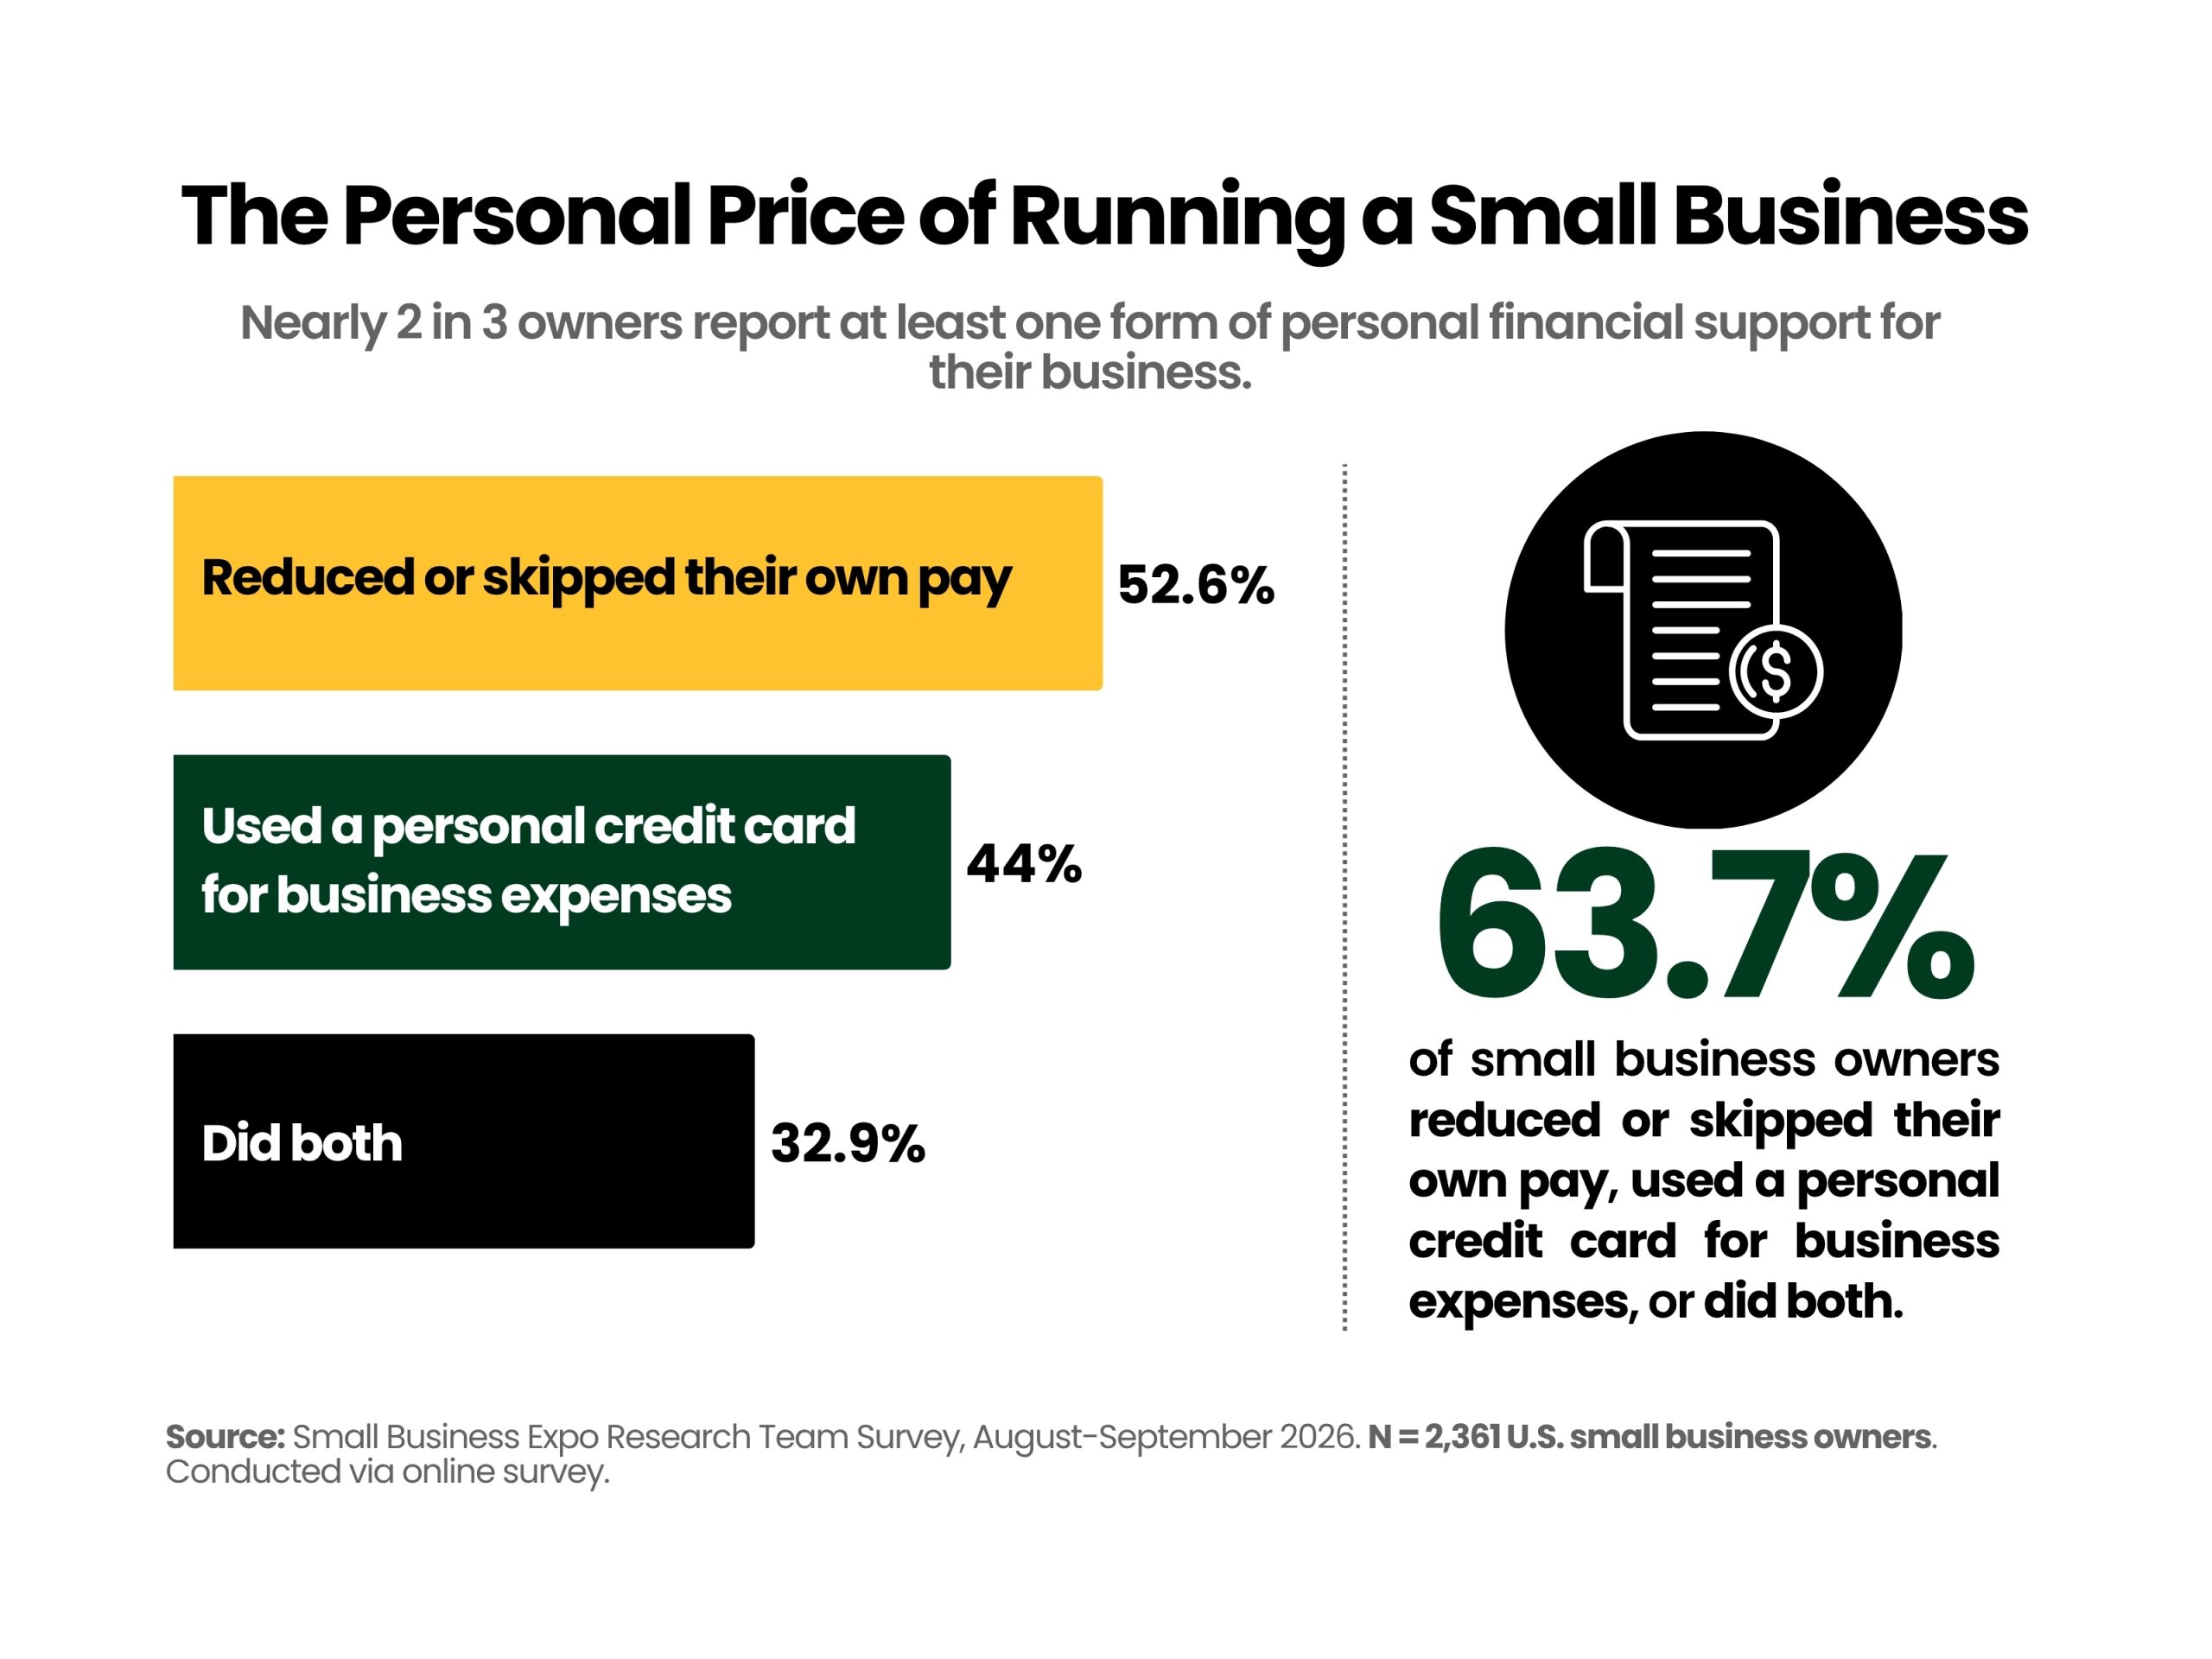
Among 2,361 small business owners surveyed, 63.7% reported at least one of two behaviors: reducing or skipping their own pay within the past year or using a personal credit card for business expenses within the past 30 days. Nearly one-third reported doing both.
The findings illustrate how frequently owners’ personal resources can become part of small business finances, particularly when money is needed to keep the business operating.
Highlights
- 63.7% reduced or skipped their own pay, used a personal credit card for business expenses, or did both.
- 52.6% reduced or skipped their own pay to keep their business running within the past year.
- 44.0% used a personal credit card to pay business expenses within the past 30 days.
- 32.9% reported both behaviors.
- Among owners who recently used personal credit cards for business expenses, 74.9% also reduced or skipped their own pay.
- Only 36.3% reported neither behavior.
More Than Half Have Sacrificed Their Own Pay
The survey asked owners whether they had reduced or skipped their own pay to keep their business running within the past year.
More than half—52.6%—said yes. That represents 1,243 of the 2,361 respondents.
The finding offers a revealing perspective on the personal side of running a business. When money is needed elsewhere in the company, an owner’s own compensation can effectively become another lever available to pull. Unlike reducing an outside expense, however, taking less pay shifts some of the financial impact directly onto the person running the business.
Federal Reserve research has also documented the role owners’ personal funds can play when businesses encounter financial challenges. Its Small Business Credit Survey tracks the use of personal funds in response to financial challenges as one measure of small business financial conditions.¹
44% Recently Used Personal Credit for Business Expenses
Personal credit is another common source of support.
44.0% of respondents said they had used a personal credit card to pay business expenses within the past 30 days.
The timeframe makes the result especially notable. This isn’t a measure of whether an owner has ever used personal credit for the business; nearly half reported doing so within a single recent month.
Personal credit and business financing frequently intersect. The Federal Reserve Banks’ 2026 Report on Employer Firms found that credit cards were the most commonly used financing product among surveyed employer firms. Among firms regularly using credit cards, 34% used both personal and business cards, while another 8% used personal cards exclusively.²
The SBA recommends maintaining separate personal and business finances, noting that dedicated business accounts and credit can make expenses easier to track and help a company establish its own financial history.³
Nearly 1 in 3 Owners Report Both Behaviors
The clearest picture emerges when the two survey questions are examined together.
32.9% of all respondents—777 owners—both used a personal credit card for business expenses within the past 30 days and reduced or skipped their own pay within the past year.
Another 30.8% reported one of the two behaviors, while just 36.3% reported neither. Together, that means 63.7%—nearly 2 in 3 respondents—reported at least one form of recent personal financial support for their business.
These behaviors do not necessarily indicate financial distress. Owners may use personal cards for convenience, rewards, or other reasons, and the survey does not establish why respondents chose particular payment methods. Still, the prevalence of these behaviors shows how frequently personal resources enter the financial picture.
Personal Credit Use and Pay Sacrifices Strongly Overlap
The connection is even clearer when comparing owners who did and did not recently use personal credit cards.
Among personal-card users, 74.9% also said they had reduced or skipped their own pay. Among those who did not use a personal card, that figure fell to 35.2%—a 39.7-percentage-point difference.
In other words, respondents using personal credit cards for business expenses were more than twice as likely to report sacrificing their own compensation.
The survey cannot establish that one behavior causes the other. What it does show is substantial overlap: these two forms of personal financial involvement frequently occur among the same owners.
Small Business Finances Often Extend Beyond the Business
Even formal business financing can depend heavily on an owner’s personal resources, making them an important part of the broader small business finances picture.
The Federal Reserve’s latest Small Business Credit Survey, for example, found that 59% of employer firms with debt used a personal guarantee to secure it, while 38% used personal assets.²
The Small Business Expo data captures another side of that relationship. Owners can effectively function as a financial buffer for their companies—whether by temporarily taking home less money or reaching for a personal credit card when an expense needs to be paid.
For a substantial share of respondents, those behaviors are happening together.
Final Takeaway
For many small business owners, the boundary between company and personal finances remains difficult to separate completely.
Nearly 2 in 3 respondents have either reduced or skipped their own pay within the past year, used a personal credit card for business expenses within the past 30 days, or done both. More than half have sacrificed their own compensation, and nearly one-third report both behaviors.
The survey doesn’t tell us whether every decision reflects financial necessity, convenience, growth investments, or other circumstances. What it does show is that small business finances frequently extend beyond the company itself and into the owner’s personal financial resources.
Footnotes
- Federal Reserve Banks. 2025 Main Street Metrics: Trends over Time from the Small Business Credit Survey.
https://www.fedsmallbusiness.org/reports/survey/2025/2025-main-street-metrics - Federal Reserve Banks. 2026 Report on Employer Firms: Findings from the 2025 Small Business Credit Survey.
https://www.fedsmallbusiness.org/2026-report-on-employer-firms - U.S. Small Business Administration. Launch Your Business.
https://www.sba.gov/counseling/launch-your-business
Related: What Would Small Business Owners Do With an Extra $80K?